
Farm & Ranch Insurance in Alamosa, CO: Protecting Farms, Ranches & Agricultural Property
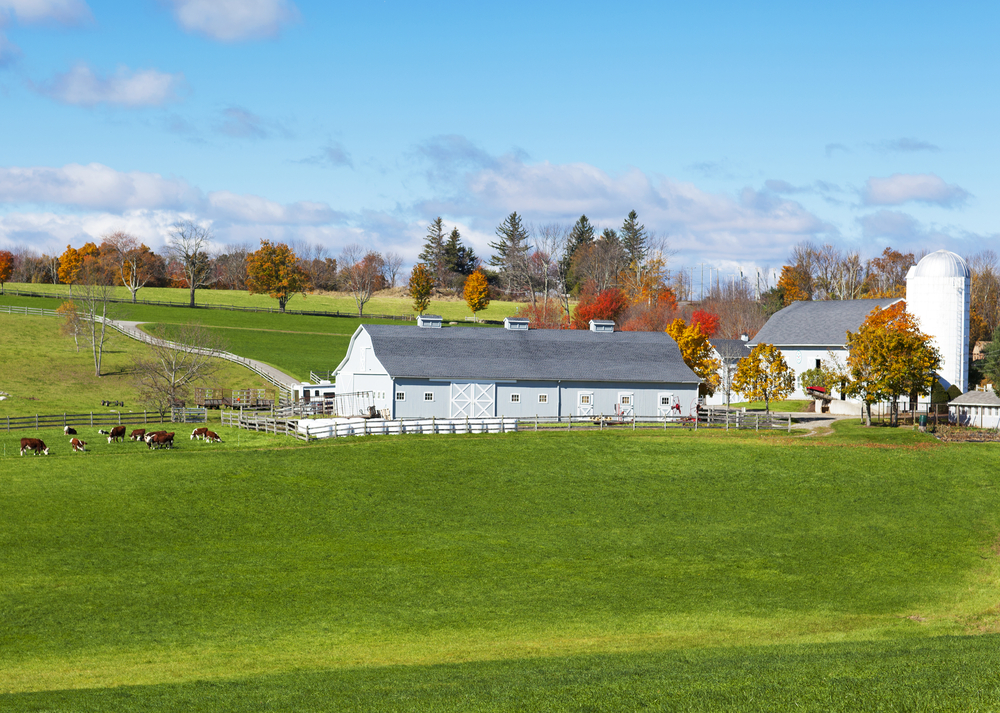
Farming and ranching in the San Luis Valley comes with risks that are different from those faced by a typical home or business. Cold winters, strong winds, hail, irrigation infrastructure, livestock, machinery, outbuildings, and wide-open acreage can all affect how agricultural property should be protected.
Farm and ranch insurance in Alamosa, CO can help protect the property, equipment, liability exposures, and other assets that keep an agricultural operation running. The right coverage depends on how the property is used, what structures and equipment are present, whether livestock is involved, and the specific risks the operation faces.
What local farmers and ranchers should know
-
A standard homeowners policy is generally not designed to address all the exposures associated with an active farm or ranch.
-
Agricultural properties in the San Luis Valley can include homes, barns, sheds, irrigation equipment, machinery, fencing, stored materials, and livestock that may require different coverage considerations.
-
Weather conditions around Alamosa County, including freezing temperatures, wind, hail, and seasonal storms, can create property and equipment risks.
-
Liability protection can be important when employees, customers, contractors, livestock, vehicles, or visitors are present on agricultural property.
-
Coverage should be reviewed when acreage, buildings, equipment, livestock, or the way the operation earns income changes.
Why Farm and Ranch Insurance Matters Locally
Farm and ranch insurance matters locally because agricultural properties around Alamosa often combine residential, commercial, and agricultural exposures on the same piece of land. That combination can make a basic home or commercial policy insufficient for the way a working property is actually used.
Properties throughout the San Luis Valley may include barns, corrals, workshops, equipment storage, irrigation systems, tractors, trailers, fencing, and livestock areas. Farms near Mosca or Hooper may have different property characteristics than ranching operations closer to La Jara, Blanca, or Fort Garland.
Seasonal conditions also matter. Low winter temperatures can contribute to frozen plumbing and equipment problems, while wind, hail, snow, and summer thunderstorms can damage roofs, siding, structures, vehicles, and machinery.
Smith Insurance helps local property owners evaluate farm and ranch insurance based on the characteristics of their operation. We can help identify coverage questions that deserve attention before a loss exposes a gap.
Local Data and Agricultural Risk Considerations
Agricultural insurance planning in the San Luis Valley should account for the area’s high-elevation climate, open terrain, seasonal temperature changes, and concentration of working agricultural property rather than relying on assumptions made for suburban homes or conventional businesses.
No Smith Insurance claims statistics or proprietary field-loss data were provided for this article, so we are not presenting specific loss percentages or frequency claims.
Instead, local property owners should evaluate risks based on their actual buildings, acreage, machinery, livestock, irrigation equipment, storage practices, business activities, and liability exposure.
How Agricultural Losses Can Affect a Local Operation
An agricultural loss can affect much more than one damaged building because farms and ranches depend on interconnected property, equipment, animals, transportation, and daily operations. Damage to one essential asset may create additional expenses or interrupt work at an especially important point in the season.
For example, damage to machinery during planting, harvesting, feeding, or irrigation periods may create more disruption than the same equipment loss would at another time of year. Damage to a barn or equipment building can also expose tools, feed, vehicles, or stored property to additional loss.
That makes it important to consider both the value of individual assets and the role each asset plays in keeping the operation functioning.
Warning Signs Your Farm or Ranch Coverage Needs a Review
Farm or ranch coverage should be reviewed when your property, operation, or financial exposure has changed since the policy was originally written. Even relatively ordinary changes can create gaps if the insurer does not have an accurate picture of the current operation.
Watch for these situations:
-
You have added a barn, shed, shop, storage building, corral, or other structure.
-
You recently purchased or replaced tractors, implements, trailers, or other expensive equipment.
-
Your livestock numbers or types have changed significantly.
-
You are storing more feed, supplies, tools, or materials on the property.
-
Customers, contractors, employees, or other visitors are coming onto the property more frequently.
-
You have changed how acreage or buildings are used.
-
You have expanded agricultural operations onto additional property.
-
You are unsure whether certain equipment or structures are specifically listed or otherwise covered by the policy.
When to Call an Insurance Professional
You should contact an insurance professional whenever a material change to your agricultural property could affect what is insured, how the property is used, or the amount of liability exposure involved. A policy review is especially useful before assuming a newly purchased building, machine, vehicle, or activity is automatically covered.
Farm and ranch owners can safely perform their own property inventory and document equipment, buildings, livestock areas, and recent improvements.
Determining whether the policy language actually protects those exposures is different. Insurance contracts contain definitions, exclusions, deductibles, limits, and conditions that should be reviewed carefully.
For agricultural property in Alamosa, a conversation before a loss can help clarify what the policy is designed to cover and where additional options may need to be considered.
Common Local Farm and Ranch Risks
Common farm and ranch risks in the San Luis Valley include severe weather, property damage, equipment losses, liability exposures, and changes in how agricultural buildings or acreage are used. The importance of each risk varies significantly from one operation to another.
1. Weather-related property damage
Wind, hail, snow, freezing temperatures, and seasonal storms can affect roofs, exterior structures, equipment, plumbing, and other exposed property.
2. Machinery and equipment exposure
Tractors, implements, tools, trailers, and specialized agricultural equipment can represent substantial investments and may be essential to daily operations.
3. Barn and outbuilding damage
Barns, workshops, storage buildings, livestock shelters, and equipment sheds should be identified accurately when evaluating property coverage.
4. Liability risks
Livestock, machinery, workers, contractors, customers, deliveries, and visitors can create liability exposures that do not exist on an ordinary residential property.
5. Changes to the operation
Expanding acreage, adding structures, purchasing equipment, changing livestock operations, or starting a new agricultural activity can change insurance needs.
Prevention and Insurance Maintenance
Good insurance maintenance starts with keeping an accurate record of the property and reviewing coverage when the operation changes. Agricultural owners should not wait until a claim occurs to discover that an important building, machine, or activity was not addressed as expected.
Before winter in Alamosa County, inspect roofs, exposed plumbing, heating systems, and structures that could be affected by snow or freezing temperatures. Before spring and summer operations increase, review machinery, fencing, irrigation-related property, and outdoor storage areas.
It is also useful to photograph buildings and major equipment periodically and maintain purchase records when possible.
Insurance questions should be handled with an agent rather than relying solely on assumptions about what a policy includes.
What to Expect From a Farm and Ranch Insurance Review
A farm and ranch insurance review should help establish a clearer picture of what you own, how the property is used, which risks matter most, and whether the current policy reflects the operation accurately.
Be prepared to discuss your residence, agricultural structures, acreage, equipment, vehicles, livestock, business activities, employees or contractors, and visitors to the property.
The goal is not simply to purchase the largest possible policy. It is to understand the available protection and make informed decisions based on your property, priorities, and budget.
Policy availability, limits, exclusions, deductibles, and eligibility can vary by insurer and individual risk.
Common Farm Insurance Mistakes
Common farm insurance mistakes usually happen when owners assume an old policy still matches a changing agricultural operation. Regular reviews can reduce the chance that important changes go unnoticed.
Mistake: Adding a structure without reviewing insurance.
Consequence: The policy may not reflect the new building or its value.
Better approach: Notify your insurance professional when significant structures are added or changed.
Mistake: Assuming every piece of equipment is treated the same.
Consequence: Coverage limits or policy terms may differ depending on the equipment.
Better approach: Review higher-value machinery individually.
Mistake: Forgetting about liability exposure.
Consequence: Visitors, livestock, business activities, or equipment can create risks beyond physical property damage.
Better approach: Discuss how people interact with the operation.
Mistake: Reviewing coverage only after a loss.
Consequence: Insurance gaps become visible when options are most limited.
Better approach: Schedule periodic reviews, particularly after major operational changes.
A Common Local Scenario
A common local scenario involves a San Luis Valley property owner who started with a residence and modest agricultural acreage but gradually added equipment, livestock, storage buildings, and other improvements. Years later, the property bears little resemblance to the operation described when the original insurance was purchased.
This is not a Smith Insurance case study or a claim about a specific customer. It illustrates why periodic coverage reviews matter.
An insurance policy should reflect the property as it exists now, not simply how it looked several years ago.
Related Farm and Ranch Insurance Solutions
Farm and ranch insurance solutions can address several types of agricultural exposure within an insurance program, depending on the policy and carrier. Relevant areas may include dwelling protection, agricultural buildings, personal or farm property, machinery, liability, and other operation-specific risks.
Not every farm needs the same coverage.
A small acreage outside Alamosa with a residence and a few outbuildings can have very different insurance needs from a larger ranch with substantial equipment, livestock, employees, or multiple agricultural structures.
Comparing Farm Insurance Options
The best way to compare farm insurance options is to look beyond price and evaluate coverage limits, deductibles, exclusions, property classifications, liability protection, and how accurately each option reflects the operation.
A less expensive policy may be appropriate when it covers the exposures that matter to you. A higher-priced option is not automatically better either.
Compare what each policy does and does not cover. Pay particular attention to major buildings, valuable machinery, livestock-related exposures, and activities that generate income or bring other people onto the property.
The appropriate choice should balance protection with the amount of risk you are comfortable retaining yourself.
Farm and Ranch Insurance Service Areas
Farm and ranch insurance needs extend throughout Alamosa and surrounding San Luis Valley communities where agricultural property remains an important part of the local landscape. Nearby areas such as Mosca, Hooper, La Jara, Monte Vista, Blanca, and Fort Garland may have similar agricultural exposures while still requiring property-specific evaluation.
Coverage availability and insurance options can vary by location and individual operation.
The Cost of Ignoring Coverage Gaps
Ignoring a potential insurance gap can leave a farm or ranch owner responsible for expenses that were assumed to be insured. The financial impact can become more significant when the damaged property is essential to agricultural operations or when a liability event involves another person.
An outdated property value, unreported building, changed use, or significant equipment purchase deserves attention before an incident happens.
For local agricultural property owners, reviewing coverage periodically is a practical part of protecting the investment that supports the operation.
Frequently Asked Questions About Farm and Ranch Insurance
Farm and ranch insurance questions are best answered by looking at the specific agricultural property because buildings, acreage, equipment, livestock, and operations vary widely throughout the San Luis Valley. These answers provide a starting point, but actual coverage depends on the terms and conditions of the policy.
What does farm and ranch insurance typically protect?
Farm and ranch insurance can provide protection for several categories of property and liability exposure, depending on the policy. These may include a residence, barns, agricultural buildings, equipment, certain personal or farm property, and liability. Exact coverage, exclusions, limits, and eligibility depend on the insurer and selected policy.
Do I need farm insurance for a small property in Alamosa?
You may need specialized farm coverage if your property in Alamosa includes agricultural activities or exposures that fall outside a conventional homeowners policy. Acreage alone does not determine the answer. Consider livestock, equipment, outbuildings, income-producing activities, employees, customers, and how the land and structures are actually used.
Does farm insurance cover tractors and agricultural equipment?
Farm insurance may provide coverage options for tractors and agricultural machinery, but the treatment of each item depends on the policy. Owners should identify major equipment and discuss its use and value rather than assuming every machine is automatically covered. High-value or specialized equipment deserves particular attention during a policy review.
Why does weather matter for farm insurance in the San Luis Valley?
Weather matters because San Luis Valley agricultural property is exposed to cold temperatures, snow, wind, hail, and seasonal storms that can affect buildings, machinery, plumbing, and outdoor property. Insurance does not eliminate weather risks, so owners should combine appropriate coverage with property maintenance and reasonable loss-prevention measures.
Should I insure every outbuilding on my Alamosa property?
Every significant outbuilding on an Alamosa agricultural property should at least be discussed during your insurance review. Barns, sheds, shops, livestock shelters, and equipment-storage buildings can have different uses and values. Your agent can explain how the policy treats each structure and whether additional information or coverage is appropriate.
How often should Alamosa County farm owners review their insurance?
Farm owners should review insurance periodically and whenever significant changes occur. Adding acreage, buying machinery, constructing a building, increasing livestock, changing business activities, or increasing the number of workers or visitors are all good reasons to revisit coverage instead of waiting for the next routine renewal.
Can farm insurance include liability protection?
Yes, farm and ranch policies can include liability protection, subject to the specific policy terms. Liability deserves careful attention because agricultural operations may involve livestock, machinery, workers, visitors, deliveries, contractors, or customers. Discussing these activities helps determine whether available liability limits and coverage options fit the operation.
Does one policy work for every ranch near Alamosa?
No, one insurance configuration does not fit every ranch near Alamosa because agricultural properties differ substantially in acreage, structures, machinery, livestock, ownership, activities, and financial exposure. Insurance should be evaluated using the actual operation rather than selecting coverage solely because another nearby farm or ranch carries something similar.
Protect Your Alamosa Farm or Ranch With Coverage Built Around Your Property
Protecting agricultural property starts with understanding what you own, how you use it, and where a financial loss could have the greatest impact. We can help you review those exposures and explore farm and ranch insurance options appropriate for your operation.